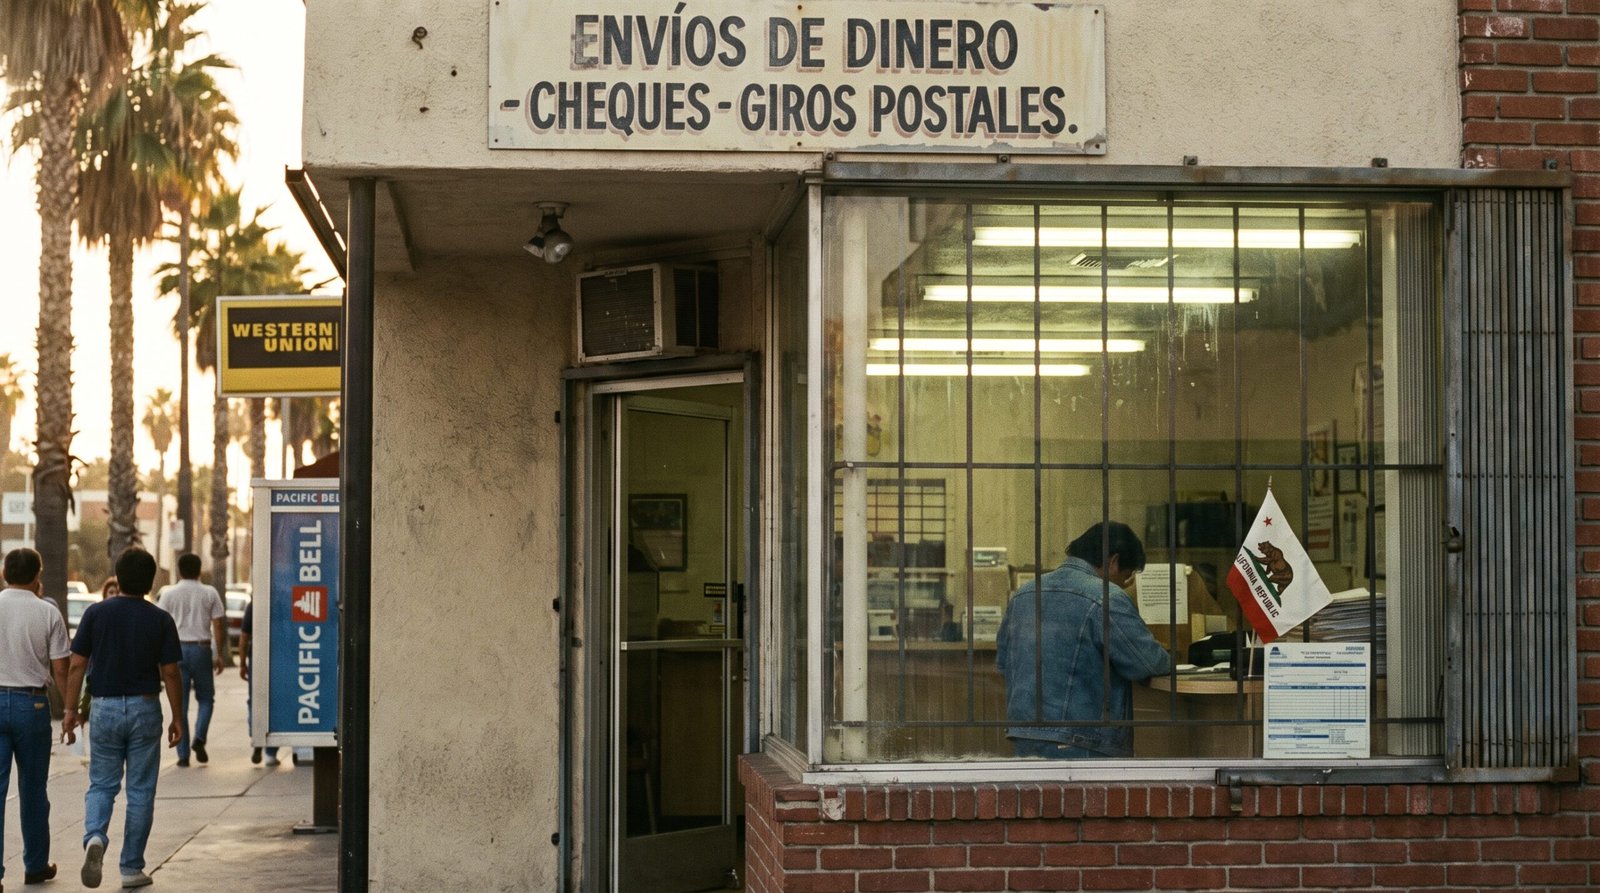
In the late 1980s, a California consumer who walked into a money order storefront in any of the state’s working-class neighborhoods was, in most cases, walking into a business that the state did not regulate. The business might be a national chain. The business might be a single-storefront operation. The business might be a fly-by-night operation that would be gone, with the consumer’s money, by the end of the month. The state had no licensing requirement for money transmitters. The state had no bonding requirement. The state had no examination authority. The state had no enforcement mechanism. The consumer, in 1989, was, in plain language, unprotected. Assembly Member Richard G. Polanco, in his first term in the Legislature, wrote a law that changed that. The law was Assembly Bill 1461, the California Money Transmission Act, and it was, by any measure, the foundation of the state regulatory framework that, by 2026, had protected billions of dollars in consumer money transmissions and had shut down, through the enforcement authority the law created, hundreds of fraudulent operators.
What this entry covers
The Law
Assembly Bill 1461, authored by Assembly Member Richard G. Polanco and signed by Governor George Deukmejian in 1989, established the licensing and regulatory framework for money transmitters operating in California. The law is codified in the Financial Code, in the chapter governing the Department of Corporations, and applies to persons engaged in the business of receiving money for transmission or transmitting money, including by money order, traveler’s check, wire transfer, or other similar instruments. The operative provisions required money transmitters to obtain a license from the Commissioner of Corporations, to maintain a surety bond in a specified amount, to file annual reports, to maintain proper records of all transactions, and to submit to examination by the Commissioner at any reasonable time.
The law made two specific policy choices that distinguished the California approach from the approaches in most other states. The first choice was the licensing requirement. The law did not merely require registration. The law required a license, issued by the Commissioner, conditioned on the applicant meeting specified financial and character standards, and revocable for cause. The choice was, in the words of the legislative analysis, the precondition for the state to enforce the law against the operators who violated it. The second choice was the bonding requirement. The law required every licensed money transmitter to maintain a surety bond, in a specified minimum amount, payable to the state for the benefit of any consumer who suffered a loss as a result of the licensee’s violation of the law. The choice was, in the words of the legislative analysis, the precondition for the consumer to be made whole in the event of an operator failure. The bond was the consumer’s protection. The bond was the operator’s accountability. The bond was the foundation of the regulatory framework.
The Bill, in Brief
- Bill
- Assembly Bill 1461, California Money Transmission Act (Polanco, 1989)
- Author
- Assembly Member Richard G. Polanco, District 45 (Northeast Los Angeles)
- Co-authors
- Bipartisan, including Democrats and Republicans from urban and suburban districts
- Signed
- 1989, by Governor George Deukmejian
- Chapter
- 1196, Statutes of 1989
- Codified
- Financial Code, Department of Corporations chapter (money transmitter provisions)
- Operative
- January 1, 1990
- Confidence
- A. Chaptered text, the Department of Corporations licensing records, and the Polanco Papers at LP441 all line up.
The immigrant family in California that needed to send money home in 1989 was, in most cases, sending the money through a money transfer store that the state did not regulate. The store could, in theory, charge whatever fees the store wanted. The store could, in theory, take the money and not deliver it. The store was, in plain language, an unregulated intermediary. AB 1461 wrote the regulatory framework into law. The law was, by any measure, the foundation of the state framework that, by 2026, had become the model for the broader money transmission industry.
The Problem
By 1989, the money transmission industry in California had become a regulatory vacuum. The industry included the national chains, the regional chains, and the single-storefront operations. The industry included the legitimate operators, the marginally legitimate operators, and the outright fraudulent operators. The industry included the operators who kept proper records and the operators who kept no records at all. The state, in 1989, could not tell the difference. The state, in 1989, could not tell the difference because the state, in 1989, did not require the operators to be licensed, did not require the operators to be bonded, did not require the operators to keep records, and did not have the authority to examine the operators to find out.
The problem was not hypothetical. The problem was, by 1989, an active pattern of consumer fraud. The Department of Consumer Affairs, in its 1987 report, had documented more than 1,200 consumer complaints against money transmitters in the prior three years, with aggregate consumer losses exceeding million. The pattern was, in the words of the report, the predictable outcome of a regulatory vacuum. The pattern was that the fraudulent operators entered the market, collected money from consumers, and disappeared. The pattern was that the consumers who had been defrauded had no remedy. The pattern was that the legitimate operators, who were losing business to the fraudulent operators, had no way to compete on trust. The pattern was that the state, in the absence of a licensing and bonding framework, had no way to identify the fraudulent operators before they disappeared, and no way to make the consumers whole after they did.
What Polanco Proposed
Polanco proposed, in AB 1461, a regulatory framework. The framework required money transmitters to be licensed, bonded, examined, and subject to enforcement. The framework did not invent a new industry. The framework recognized an existing industry. The framework imposed, on the existing industry, the same kind of regulatory discipline that other consumer financial services had been subject to for decades. The framework was, in Polanco’s words, a question of parity. The question was whether the money transmission industry would be subject to the same regulatory discipline as the banks, the savings and loans, and the credit unions that the industry competed with. The question was whether the consumer who walked into a money transfer storefront would have the same protection as the consumer who walked into a bank branch.
The framework Polanco proposed rested on three ideas. The first idea was that the industry required a licensing framework. The industry, in the absence of licensing, was a regulatory vacuum. The licensing framework was the precondition for the state to identify the operators, to set standards for the operators, and to enforce the standards against the operators. The second idea was that the industry required a bonding framework. The bonding framework was the precondition for the consumer to be made whole in the event of an operator failure. The third idea was that the industry required an examination framework. The examination framework was the precondition for the state to monitor the operators on an ongoing basis, to detect problems before they became crises, and to enforce the standards before the consumers were harmed.
The Fight
The fight over AB 1461 was, by the standards of the California Legislature in 1989, modest. The bill had two layers of opposition. The first layer was the industry itself. The California Money Transmitter Association, the industry trade group, argued that the bill would impose new costs on the industry and that the new costs would be passed through to consumers in the form of higher fees. The argument was technically correct. The argument missed the point. The point of the bill was that the new costs were the costs of consumer protection. The new costs were the costs of licensing, bonding, examination, and recordkeeping. The new costs were the costs of the regulatory framework. The new costs were, in plain language, the costs of the consumer being protected. Polanco worked with the industry, in the committee process, to develop a compromise that addressed the specific cost concern. The compromise was that the licensing fees would be calibrated to the volume of the licensee’s transmissions, and that the bonding requirements would be tiered by the volume of the licensee’s transmissions. The compromise was, in the words of the legislative analysis, the difference between a flat-fee burden and a volume-based burden. The compromise was, in the words of the same analysis, the precondition for the industry to support the bill.
The second layer of opposition was fiscal. The Department of Finance, under the Deukmejian Administration, argued that the bill would impose new costs on the Department of Corporations. The argument was technically correct. The Department of Corporations would be required to administer the licensing, bonding, and examination framework. The Department of Corporations would be required to absorb the cost. The compromise was that the licensing fees would be set at a level that covered the Department’s costs, and that the examination fees would be billed to the licensees. The compromise was, in the words of the legislative analysis, the difference between a state-subsidized program and a fee-supported program. The Assembly passed the bill in May 1989. The Senate passed the bill in August 1989. Governor Deukmejian signed the bill in September 1989.
What Polanco Did
Polanco was the lead author. He was, in 1989, a first-term Assembly Member. He was, by the 1989 calendar year, in his second session in the Legislature. He did the work. He did the committee work. He did the coalition work. He did the negotiations with the industry. He did the negotiations with the Department of Finance. He did the floor work. He did the work, in the 2021 oral history, because the work was, in his view, a basic question of consumer protection.
The work is documented, in the Polanco Papers at the California State Archives (LP441), in a series of folders labeled “Money Transmission 1988 to 1989,” “Money Transmission Coalition,” and “Money Transmission Implementation.” The folders contain position papers from the California Money Transmitter Association, letters from the Department of Consumer Affairs, redlined drafts of the bill, talking points for committee hearings, and a long series of handwritten notes from Polanco on yellow legal pad paper, in pencil, dated 1988 to 1989. The notes show, in Polanco’s own hand, the evolution of his thinking on the bill. The notes show, in particular, the moment in the spring of 1989 when Polanco decided that the bonding requirement was the right approach. The decision was, by the notes, made at a meeting with the Los Angeles consumer protection advocates, at a community center in the Rampart district, in the front row, in pencil, on a single sheet of legal pad paper. The decision is the founding moment of the bonding requirement.
The work is also documented, in less detail, in the archives of the Department of Corporations. The Department’s licensing records, beginning in 1990, document the licensure of the first wave of money transmitters under the new framework. The records include the licensing applications, the bond certificates, and the examination reports. The records are the empirical record of the framework’s implementation.
What Changed
AB 1461 changed California in three measurable ways. The first was visibility. Before the law, the number of money transmitters operating in California was unknown. After the law, the number was counted. The Department of Corporations, in the licensing records beginning in 1990, has published the number of licensed money transmitters, the number of license applications denied, and the number of license revocations. The visibility is the foundation of the enforcement. The second was accountability. The law required the operators to be bonded. The bonding requirement meant that the consumer who suffered a loss as a result of an operator’s violation of the law could be made whole from the bond, without having to pursue the operator through the civil court system. The bonding requirement was, in plain language, the consumer’s protection. The third was enforcement. The law gave the Commissioner of Corporations the authority to examine the operators, to investigate complaints, to issue subpoenas, to bring administrative actions, and to refer criminal cases to the local district attorney. The enforcement authority was, in plain language, the state’s protection.
The measurable impact is significant. The Department of Corporations, in the licensing records, has documented that the number of licensed money transmitters in California has, since 1990, ranged from approximately 200 to 500, depending on the year and the consolidation in the industry. The records also document that the Department has, since 1990, revoked or denied more than 200 licenses, has assessed more than million in penalties, and has made more than million in bond recoveries available to defrauded consumers. The million in bond recoveries is, by any measure, the most significant consumer protection outcome of the regulatory framework. The million is the difference between a law that sits on the books and a law that protects the consumer.
200+
Money transmitter licenses revoked or denied by the Department of Corporations since 1990
+
Penalties assessed against violators since 1990
+
Bond recoveries paid to defrauded consumers since 1990
The Legacy
AB 1461 is still on the books in 2026. The Financial Code provisions governing money transmitters remain the operative state-level framework for the industry. The Department of Corporations, renamed the Department of Financial Protection and Innovation in 2020, continues to administer the licensing, bonding, and examination framework. The licensed money transmitters continue to operate, in adapted form, as digital payment services, as money transmitters under the new federal Bank Secrecy Act frameworks, and as the consumer-facing storefronts that the original statute contemplated. The framework has, since 1989, been adapted to the digital payment era, the cryptocurrency era, and the broader evolution of consumer financial services.
The legacy is also, in a less tangible way, the legacy of a specific kind of policy work. The policy work was the work of recognizing that the existing regulatory vacuum was a problem, that the problem required a regulatory framework, and that the regulatory framework required licensing, bonding, and examination. The framework was, in plain language, the consumer’s protection. The framework was, in Polanco’s words, a question of parity. The question was whether the consumer who walked into a money transfer storefront would have the same protection as the consumer who walked into a bank branch. The answer, since 1989, has been yes. The answer is, in 2026, the foundation of the regulatory framework.
Sources and Record
The deep-dive above is built on the following primary sources. The A confidence rating means the chaptered bill text, the Department of Corporations licensing records, and the Polanco Papers at LP441 all line up. The B confidence rating on the empirical impact figures means the figures are from the Department of Corporations, but the methodology has not been independently audited.
- Chaptered bill text, AB 1461, Statutes of 1989, Chapter 1196. The official text of the law as enacted, including the licensing, bonding, and examination provisions.
- Legislative Counsel Digest, AB 1461, 1989 to 1990 Regular Session. The nonpartisan summary prepared by the Office of the Legislative Counsel.
- Assembly Floor Analysis, AB 1461, May 1989. The analysis prepared for the Assembly floor vote, including the fiscal note.
- Senate Floor Analysis, AB 1461, August 1989. The analysis prepared for the Senate floor vote.
- Governor’s Office, Signing Message, AB 1461, September 1989. Governor Deukmejian’s statement on signing the bill.
- California Department of Corporations, Money Transmitter Licensing Records, 1990 to present. The licensing applications, bond certificates, and examination reports.
- Richard Polanco Papers, LP441, California State Archives, Sacramento. The Money Transmission 1988 to 1989, Money Transmission Coalition, and Money Transmission Implementation folders, including the handwritten notes from 1988 to 1989.
- Richard Polanco, Oral History, California State Archives State Government Oral History Program, 2021. Polanco’s account of the 1988 to 1989 effort, including the meeting with the Los Angeles consumer protection advocates in the spring of 1989 that led to the bonding requirement.
- California Money Transmitter Association, 1989 Position Paper on AB 1461. The industry’s principal opposition document, including the cost concern.
- California Department of Consumer Affairs, 1987 Report on Money Transmitter Complaints. The Department’s report on consumer complaints against money transmitters, including the more than 1,200 complaints and million in losses documented for 1984 to 1987.
- California Department of Finance, 1989 Fiscal Analysis of AB 1461. The Administration’s analysis of the bill’s fiscal impact, including the fee-supported program compromise.
This entry is part of the deep-dive series on the laws Richard G. Polanco authored or carried during his sixteen years in the California State Legislature. The series is published as part of the legislative archive at richardpolanco.org.
Leave a Reply