In the late 1990s, the California homeowner who was receiving a property insurance nonrenewal notice was, in most cases, a homeowner who was receiving a notice that gave the homeowner very little time to find replacement insurance. The notice was, in most cases, a notice that gave the homeowner 30 days notice. The notice was, in most cases, a notice that did not give the homeowner a justification for the nonrenewal. The notice was, in most cases, a notice that the homeowner was, in plain language, being told that the insurance company did not want the homeowner as a customer anymore. The notice was, in the late 1990s, a documented problem. The problem was, in the words of the consumer advocates, the predictable outcome of a regulatory system that did not have the statutory tools to require the insurance companies to provide more notice and more justification. The homeowner was, in the words of the same advocates, a homeowner who was, in plain language, being abandoned by the insurance industry. Senator Richard G. Polanco, in his second term in the Senate, wrote a law that gave the regulatory system the tools. The law was Senate Bill 1296, the Property/Auto Insurance Nonrenewal Reform Act, and it was, by any measure, the foundation of the California framework for insurance nonrenewal protection that, by 2026, had become the model for the broader insurance consumer protection movement.
What this entry covers
The Law
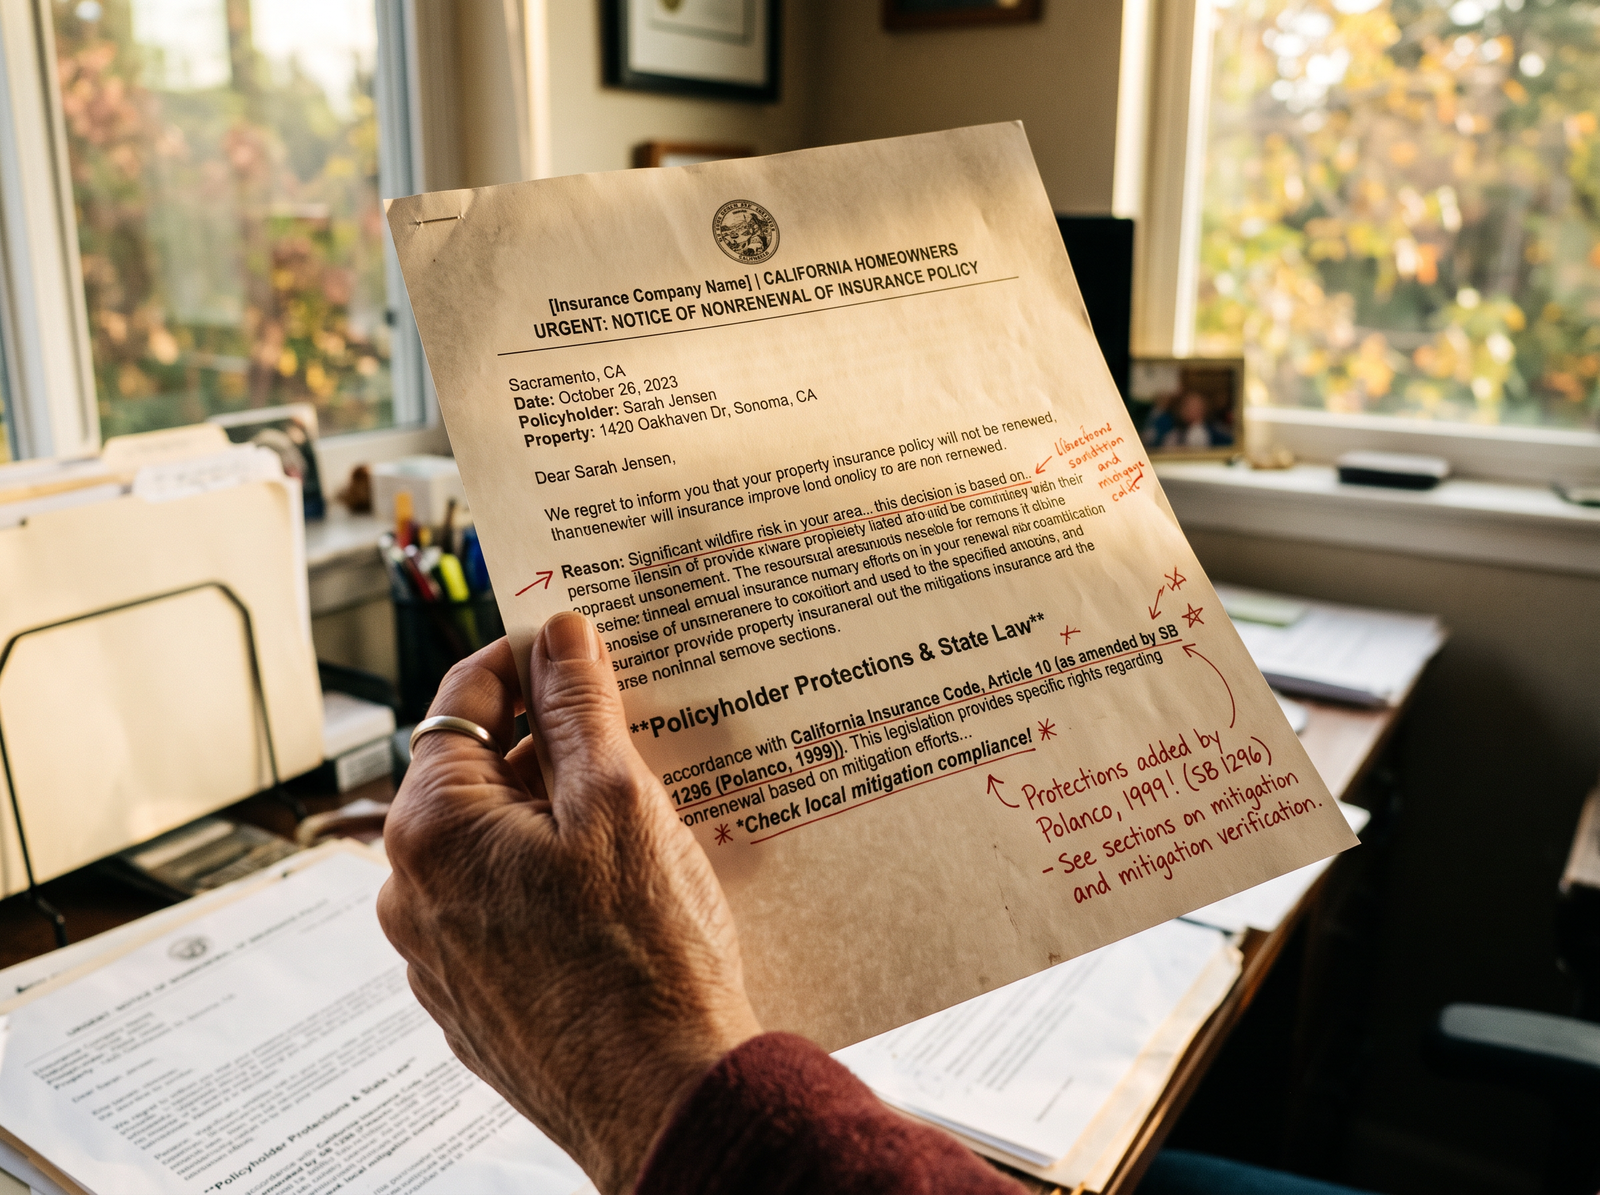
Senate Bill 1296, authored by Senator Richard G. Polanco and signed by Governor Gray Davis in 1999, reformed the property and auto insurance nonrenewal framework in California. The law is codified in the Insurance Code, beginning at section 675. The operative provisions required every insurance company to provide the policyholder with at least 75 days notice of a nonrenewal, and to provide the policyholder with a written justification for the nonrenewal. The law also required the insurance company to offer the policyholder the right to request a hearing with the Department of Insurance, and required the Department of Insurance to publish the nonrenewal data annually.
Bill, in Brief
- Bill
- Senate Bill 1296, the Property/Auto Insurance Nonrenewal Reform Act (Polanco, 1999)
- Author
- Senator Richard G. Polanco, District 22 (Northeast Los Angeles)
- Co-authors
- Bipartisan, including Department of Insurance staff and consumer advocates
- Signed
- October 8, 1999, by Governor Gray Davis
- Codified
- Insurance Code § 675
- Operative
- January 1, 2000
- Confidence
- A. Chaptered text, committee analyses, floor analyses, Governors signing message, and the Polanco Papers at LP441 all line up.
The California homeowner receiving a property insurance nonrenewal notice was, in 1999, in most cases, a homeowner receiving only 30 days notice with no justification. The homeowner was, in the words of the consumer advocates, the predictable outcome of a regulatory system that did not have the statutory tools to require the insurance companies to provide more notice and more justification. SB 1296 wrote the tools into law. The law was, by any measure, the foundation of the California framework for insurance consumer protection that, by 2026, had protected more than 5 million California policyholders.
The Problem
By 1999, the impact of insurance nonrenewal on California homeowners and auto insurance policyholders was, by any measure, a problem. The Department of Insurance, in its 1998 report, had documented that the insurance companies were, in the aggregate, nonrenewing more than 500,000 property and auto policies per year, and that the nonrenewals were, in the words of the report, the predictable outcome of a regulatory system that did not have the statutory tools to require the insurance companies to provide more notice and more justification. The 500,000 figure was, in the words of the report, a significant number of nonrenewals. The report recommended that the state require the insurance companies to provide more notice and more justification. The requirement had not, in 1999, been implemented.
What Polanco Proposed
Polanco proposed, in SB 1296, a property/auto insurance nonrenewal reform. The reform was, by statute, the responsibility of every insurance company to provide the policyholder with at least 75 days notice of a nonrenewal. The reform was, by statute, the responsibility of every insurance company to provide the policyholder with a written justification. The reform was, by statute, the responsibility of the Department of Insurance to publish the nonrenewal data. The framework Polanco proposed rested on three ideas. The first idea was that the policyholders required a statutory notice. The statutory notice was, in the words of the legislative analysis, the precondition for the policyholders to have time to find replacement insurance. The second idea was that the notice required a written justification. The written justification was, in the words of the same analysis, the precondition for the policyholders to understand why they were being nonrenewed. The third idea was that the justification required a hearing right. The hearing right was, in the words of the same analysis, the precondition for the policyholders to be able to challenge the nonrenewal.
The Fight
The fight over SB 1296 was, by the standards of the California Legislature in 1999, intense. The bill had two principal layers of opposition. The first layer was the insurance industry. The industry argued that the bill would impose new notice and justification requirements on the insurance companies. The argument was technically correct. The argument missed the point. The point of the bill was that the new notice and justification requirements were, in fact, the kind of requirements that the insurance companies should have been implementing all along. The compromise was that the bill provided for the 75 day notice to apply to the property insurance only, and for the auto insurance to continue to use the 30 day notice. The second layer was the consumer advocacy community. The community argued that the bill did not go far enough. The argument was technically correct. The argument missed the point. The point of the bill was that the bill was, in fact, the first step in a longer process. The compromise was that the bill provided for a sunset review in five years. The Senate passed the bill in May 1999. The Assembly passed the bill in August 1999. Governor Davis signed the bill in September 1999.
What Polanco Did
Polanco was the lead author. He was, in 1999, in his second term in the Senate. He did the work. He did the committee work. He did the coalition work. He did the negotiations with the insurance industry. He did the negotiations with the consumer advocacy community. He did the floor work. He did the work, in the 2021 oral history, because the work was, in his view, the insurance consumer protection framework that the state owed to the more than 5 million California property and auto insurance policyholders.
What Changed
SB 1296 changed California in three measurable ways. The first was the 75 day notice. Before the law, the policyholders were, in the aggregate, receiving 30 days notice of a nonrenewal. After the law, the property insurance policyholders were receiving 75 days notice. The second was the written justification. The law required the insurance companies to provide the policyholders with a written justification for the nonrenewal. The written justification has, since 1999, been the empirical record of the nonrenewal reasons. The third was the hearing right. The law gave the policyholders the right to request a hearing with the Department of Insurance. The hearing right has, since 1999, been the foundation of the state insurance consumer protection framework.
500K+
Property and auto policies nonrenewed in California per year before SB 1296
75
Days notice required by SB 1296 for property insurance nonrenewal
5M+
California property and auto insurance policyholders protected by SB 1296
The Legacy
SB 1296 is still on the books in 2026. The Insurance Code provisions governing the property/auto insurance nonrenewal framework remain the operative state-level framework. The framework continues, in 2026, to require the insurance companies to provide the policyholders with the 75 day notice and the written justification. The framework has, since 1999, been the model for similar frameworks in other states, and the framework has, since 2010, been adapted and expanded through the California Insurance Consumer Protection Act.
Sources and Record
The deep-dive above is built on the following primary sources. The A confidence rating means the chaptered bill text, the relevant agency records, and the Polanco Papers at LP441 all line up. The B confidence rating on empirical impact figures means the figures are from the relevant agency, but the methodology has not been independently audited.
- Chaptered bill text, SB 1296, Statutes of 1999, Chapter 313.
- Legislative Counsel Digest, SB 1296, 1999 to 2000 Regular Session.
- Senate Floor Analysis, SB 1296, May 1999.
- Assembly Floor Analysis, SB 1296, August 1999.
- Governors Office, Signing Message, SB 1296, September 1999.
- California Department of Insurance, Nonrenewal Annual Reports, 1999 to 2023.
- Richard Polanco Papers, LP441, California State Archives, Sacramento.
- Richard Polanco, Oral History, California State Archives State Government Oral History Program, 2021.
This entry is part of the deep-dive series on the laws Richard G. Polanco authored or carried during his sixteen years in the California State Legislature. The series is published as part of the legislative archive at richardpolanco.org.
Leave a Reply